
KiwiSaver withdrawal options
While KiwiSaver is designed to help you save for your retirement, in very specific circumstances you may be able to access your KiwiSaver savings before you reach 65.
As your KiwiSaver provider, AMP can help you understand whether you’re eligible and can help you with the KiwiSaver withdrawal rules and processes if you are. In particularly challenging cases we can even refer you to specialists for help.
Situations that may enable you to withdraw from your KiwiSaver account include:
- Retirement: You can withdraw some or all of your KiwiSaver savings when you turn 65 (and meet other eligibility requirements).
- First home: You may be able to withdraw almost all your savings to purchase your first property.
- Hardship: You may be granted an early withdrawal in extenuating circumstances, such as financial hardship.
Making a retirement withdrawal from KiwiSaver
When can I withdraw my retirement savings from KiwiSaver?
You can currently withdraw from the KiwiSaver scheme when you turn 65, but for those who joined KiwiSaver (or a complying superannuation fund) before 1 July 2019, the qualifying date is the latter of:
- The qualifying age for New Zealand Superannuation (currently 65);
- Five years after you first joined KiwiSaver (or a complying superannuation fund if you have transferred to KiwiSaver from another country’s scheme);
- Five years after Inland Revenue received your first contribution (whether employer contribution or voluntary contribution).
If you are over 65 but haven’t yet reached your qualifying date, you can choose to bring it forward, but you will lose eligibility for government and employer contributions from that date.
The process of withdrawing from KiwiSaver after retirement
Having reached the qualifying age, you have three KiwiSaver withdrawal options in retirement:
Regular
Pay yourself from your KiwiSaver savings, withdrawing a specific amount at regular intervals (monthly/fortnightly/quarterly).
Partial
Withdraw a lump sum from your KiwiSaver savings only when you need to.
Full
Withdraw all of your KiwiSaver savings at once and close your KiwiSaver account.
Why keep money in your KiwiSaver account after you retire? The money in your KiwiSaver account is invested, so it can generate compounding returns! This is why many KiwiSaver members choose to only take out what they need with regular or partial withdrawals.
To make your first retirement withdrawal, complete the initial retirement withdrawal process on MyAMP. Send us the completed form with supporting documents (ID, statutory declaration*), and we’ll do the rest. You should see your money in 8-15 days, once IRD has processed your application.
*If you are an overseas based customer, you will also need to supply proof of your residential address.
Subsequent withdrawals are simpler: just fill out our subsequent retirement withdrawal form online. As the Statutory Declaration has already been completed, it does not need to be completed subsiquently. This means the request can be processed faster as a result.
Withdrawing KiwiSaver when buying your first home
Your KiwiSaver savings can be used to help you buy your first home, or land to build your first home on, provided you…
- are buying a New Zealand property
- have never owned a property or made a first home withdrawal before
- will live in the house or on the land you’re buying (no investment properties)
- have participated in KiwiSaver for at least three years
- aren’t building on land you already own
If you’re eligible to make a KiwiSaver first home withdrawal, you’ll just need to leave at least $1,000 in your KiwiSaver account, as well as any money transferred over from an international retirement scheme, such as Australian super or the UK pension.
How to make a KiwiSaver first home withdrawal
To make a first home withdrawal from your KiwiSaver account, fill out the first home withdrawal application form and send it to your KiwiSaver Scheme provider (AMP) with the following supporting documents:
- A copy of the sale and purchase agreement.
- Proof of identity.
- A letter of undertaking from your solicitor.
- Your solicitor’s trust account details.
You can leave the rest to us! Approval usually takes 8-15 days, at which point the funds will be transferred to your solicitor’s account.
KiwiSaver withdrawal due to extenuating circumstances
Beyond retirement and purchasing your first home, you may be allowed to access funds from your AMP KiwiSaver Scheme account in very specific extenuating circumstances, but only ever as a last resort, when all other avenues have been exhausted:
Significant financial hardship
If you are suffering, or are likely to suffer from financial hardship, then you may be eligible for a significant financial hardship withdrawal from your AMP KiwiSaver Scheme savings. A Supervisor will determine whether you can make the withdrawal, and the amount you can withdraw, based on your circumstances. Your eligibility may include minimum living expenses, debt repayments and liabilities.
Significant Financial Hardship Withdrawal
Serious illness
If you are suffering from a serious illness, you may be able to make a serious illness withdrawal. This grants you access to some or all of your savings to help cover lost income and the costs of medical treatment. The decision is based on medical evidence reviewed by the Supervisor.
Serious illness withdrawal form
Life-shortening congenital conditions
Similar to the above, if you are suffering from a life-shortening congenital condition you may withdraw some or all of your savings, though the amount is dependent on whether you have a listed or unlisted condition.
Life-shortening congenital conditions withdrawal form
Permanent emigration to Australia
If you permanently emigrate to Australia, you can transfer all of your KiwiSaver savings to an Australian complying superannuation scheme. (It’s important to first confirm with your Australian provider that they will accept a transfer, as not all do.)
Permanent emigration transfer application form (Australia)
Permanent emigration elsewhere
A year after you permanently emigrate from New Zealand to another country (other than Australia), you may withdraw your KiwiSaver savings minus any Government contributions and money that you previously transferred over from an Australian super fund.
Permanent emigration transfer application form (not Australia)
Withdrawal of Australian retirement savings
If you have reached the age of 60, and you have retired under Australian law, you can access any retirement funds that you have transferred over to KiwiSaver from an Australian super fund.
Retirement withdrawal form (Australian sourced savings)
Death
In the event of your death, your KiwiSaver savings will be paid to your estate, or if your savings are less than a prescribed minimum amount (currently $15,000), the funds may be paid to the bank account of a permitted recipient, such as a partner or family member.
Deceased withdrawal form
Find out more by downloading our AMP KiwiSaver Scheme Product Disclosure Statements.
The process of withdrawing from KiwiSaver in extenuating circumstances
Your specific extenuating circumstances will define the process of accessing your KiwiSaver savings, and a range of criteria, rules and exclusions apply to each circumstance. It’s wise to speak to our KiwiSaver advisers before making any decision, to gain a better understanding of whether it’s the right move for you.
If you believe you meet eligibility requirements, you can apply to make a withdrawal using the form links above.
Generally speaking, a licensed Supervisor will review your completed application and supporting documentation. If satisfied, they will also decide exactly how much money you are permitted to withdraw from your KiwiSaver account.
Looking for expert KiwiSaver advice?
We recommend speaking to a financial adviser before making any KiwiSaver withdrawal, to gain professional financial planning advice, and to understand the most beneficial plan for your situation.
We recommend speaking to a financial adviser when looking for financial advice. By speaking with a financial adviser, you can find out how your plan is working (or not) for you, and they can provide guidance on some suggested changes if needed.
As an AMP KiwiSaver Scheme customer you have access to financial advice whenever you need it which can be obtained either through AMP or an external Adviser. The financial advice that can be provided by an internal AMP Adviser is limited to AMP products, whereas an external Adviser may be able to advise you on a broader range of financial matters.
Keep track of your KiwiSaver savings
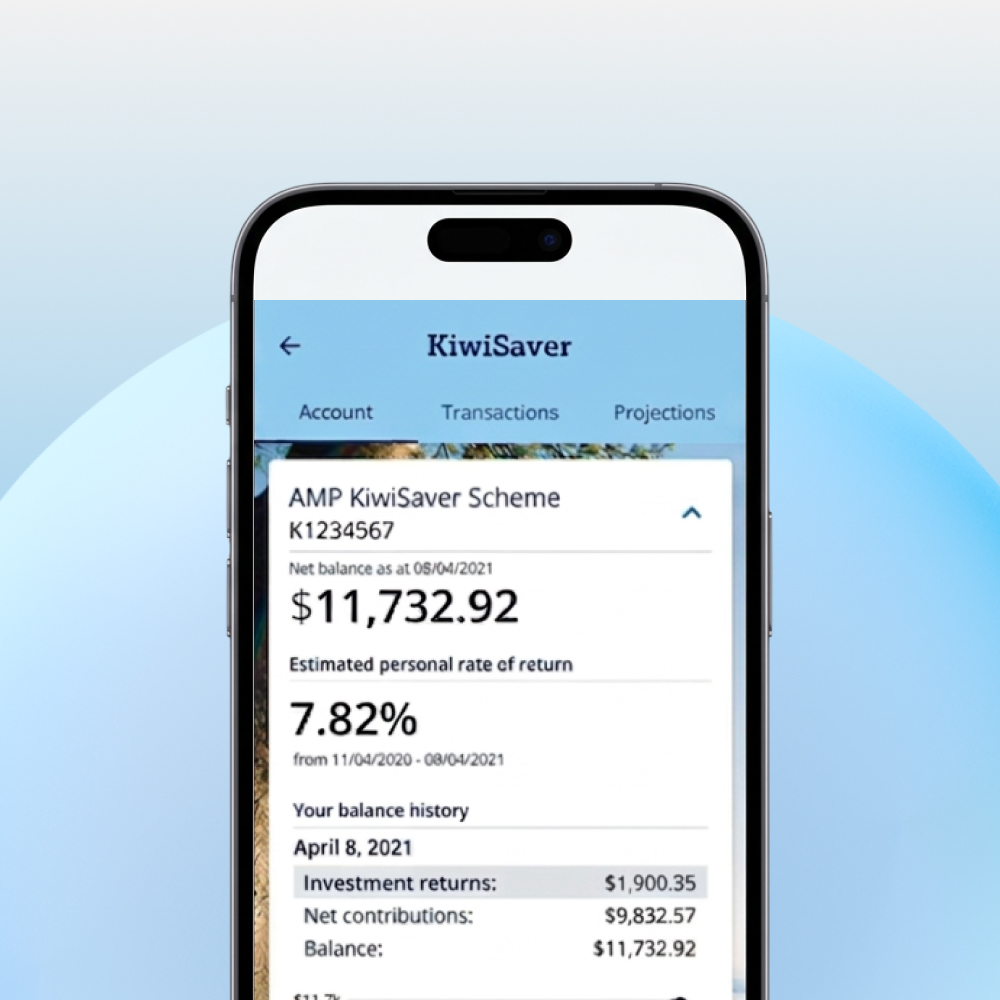
Our online portals, MyAMP and the MyAMP app, make it simple to check and manage your AMP KiwiSaver Scheme account. You Watch how your savings perform over time, update your personal details, change direct debit KiwiSaver contributions and switch investment funds in clicks!
Want to take a break from contributing?
As an employee, you can take a break from contributing to your AMP KiwiSaver Scheme account. You could either take:
- a ‘savings suspension’ – for 3 months up to 12 months if you’ve been a member for 12 months or more
- an ‘early savings suspension’ - If you’ve been a member for less than 12 months, and are experiencing financial difficulty
If you stop contributing, you may miss out on benefits such as employer contributions and Government contributions. To find out more or apply for a ‘savings suspension’, you can contact Inland Revenue on 0800 549 472.
Frequently asked questions
What are the 3 reasons you can withdraw money from KiwiSaver?
The three main reasons for accessing your KiwiSaver savings are:
- Retirement: Once you turn 65 (and meet other eligibility requirements) you gain complete control over your KiwiSaver savings.
- First home: As an eligible first home buyer you can access most of your KiwiSaver savings to help with the purchase of your first home.
- Extenuating circumstances: Your KiwiSaver savings may be used as a last resort in several extenuating circumstances such as financial hardship, serious illness or permanent emigration.
Can I withdraw my KiwiSaver savings to pay off my debt?
As a general rule, you cannot use your KiwiSaver savings to pay off debt. The only exception would be a financial hardship withdrawal, at which point a licenced Supervisor would determine whether you can access your KiwiSaver savings, and exactly how much you can take out.